From I-95 nor’easters to severe summer thunderstorms, Wilmington’s weather routinely strips roof shingles across Brandywine Hills and Trolley Square. After a major weather event, one question hits every homeowner fast: Does homeowners insurance cover roof damage?
The answer is yes, but only under specific conditions. In 2026, a full roof replacement in Wilmington costs $10,000 to $15,000, and partial repairs run $2,400 to $5,500.
Whether does homeowners insurance covers roof damage from your storm depends on the cause of loss, your policy type, and, critically, how quickly you act.

What Homeowners Insurance Covers for Roof Damage
When Wilmington homeowners ask, “Does homeowners insurance cover roof damage?”
The answer hinges on one word: suddenness.
Standard HO-3 policies, per the Delaware Insurance Guide, cover sudden, storm-caused events, not gradual deterioration.
Covered perils under most Delaware HO-3 policies:
- Wind damage: missing or lifted shingles from gusts above 50 mph
- Hail impact: cracked or dented asphalt shingles
- Lightning strikes: structural burn or fire damage
- Falling objects: tree limbs or wind-driven debris
What’s typically NOT covered:
- Gradual wear and tear on roofs 20+ years old
- Maintenance neglect or pre-existing damage
- Undocumented slow leaks with no storm event on record
Adjusters cross-reference claims against National Weather Service records.
No documented storm event, no covered claim.
2026 Storm Roof Repair Costs in Delaware
Knowing your numbers helps you decide whether homeowners insurance covers roof damage at a value actually worth filing for.
|
Repair Type |
2026 Cost Range |
|
1 to 10 shingles replaced |
$350 to $850 |
|
Flashing repair or replacement |
$550 to $850 |
| Emergency tarping |
$400 to $800 |
|
Partial repair (10 to 25% of roof) |
$2,400 to $5,500 |
| Full roof replacement |
$10,000 to $15,000 |
Note: Actual repair costs may vary based on your specific location within Delaware, roof pitch, and current material prices.
Emergency tarping costs $400 to $800 and is often reimbursable under your policy’s “protect from further damage” clause.
However, you must take time-stamped photos of all visible damage before any temporary work begins.
Storm hit your Wilmington home?
Find Rain Drainz on Google Maps for fast storm damage inspections across Delaware.
How to File a Roof Damage Insurance Claim Correctly
Filing a damage insurance claim for your roof the right way from day one determines your payout.
- Document before cleanup: Time-stamped photos and video of every damaged area, including interior water stains.
- Get an independent inspection: A licensed Wilmington roofer’s written report gives you leverage before the adjuster arrives.
- Know your deductible: Delaware policies commonly include a separate wind/hail deductible of 1% to 2% of insured value. On a $350,000 home, that’s $3,500 to $7,000 out-of-pocket before coverage applies.
- Report promptly: Most policies require you to give notice “as soon as practicable.” While there isn’t a strict 30-day deadline, waiting too long can give the insurer grounds to deny your claim if the delay causes further damage.
So, does homeowners insurance cover roof damage in full?
Yes, when documentation is complete and submitted on time.
For a complete post-storm walkthrough, refer to the Wilmington storm damage roof repair guide.
What NOT to Say to Your Insurance Adjuster
Knowing what not to say to a roof insurance adjuster can protect thousands of dollars in your final settlement.
- Don’t mention ongoing issues: It opens a pre-existing condition argument that weakens your storm claim.
- Don’t guess at the timeline: Only state that you noticed damage after the documented storm event.
- Don’t accept the first estimate as final: Adjusters represent the insurer’s interest, not yours.
- Don’t sign anything immediately: Supplemental claims can still be added after a thorough independent inspection.
Pro Tip from Rain Drainz: Need documentation that holds up against an adjuster?
Rain Drainz’s local roofers near you deliver detailed written inspection reports built specifically to support insurance claims.
Does Insurance Cover Roof Leaks?
Whether insurance covers roof leaks depends entirely on the source.
A leak driven by wind-forced rain during a documented storm near Wilmington’s Christina River waterfront is cored.
A slow drip from deteriorated flashing that’s been seeping for two seasons is not covered.
Wilmington’s 60+ mph summer storms force water under ridge caps and chimney flashing, creating storm-caused leaks that are fully claimable.
Get them documented by a certified roofer before the adjuster closes your file.
The Claim Deadlines Wilmington Homeowners Can’t Miss
This is where most homeowners lose money: does homeowners insurance cover roof damage filed months after a storm?
Most Delaware policies follow these deadlines:
- 30 days: Report damage promptly after discovery.
- 2 months: Most wind and hail policies require you to file your claim within 365 days of the storm. You typically have that same 12-month window to complete repairs if you want to recover your full Replacement Cost Value (RCV) depreciation.
- 3 years: Delaware’s breach-of-contract statute of limitations under 10 Del. C. § 8106.
Miss the 12-month policy window and your insurer can deny the claim entirely, regardless of how visible or severe the damage is.
Key Takeaways
- Does homeowners insurance cover roof damage? Yes, for sudden events like wind, hail, and lightning.
- Standard HO-3 Delaware policies cover storm perils; wear and tear is excluded.
- Wind/hail deductibles of 1% to 2% of insured value are common across Delaware.
- Emergency tarping at $400 to $800 is reimbursable when documented before temporary repairs begin.
- Report damage within 30 days. File your claim and complete repairs within 12 months of the storm date to recover full RCV depreciation.
- An independent roofer’s inspection report, secured before the adjuster visits, directly strengthens your claim value.
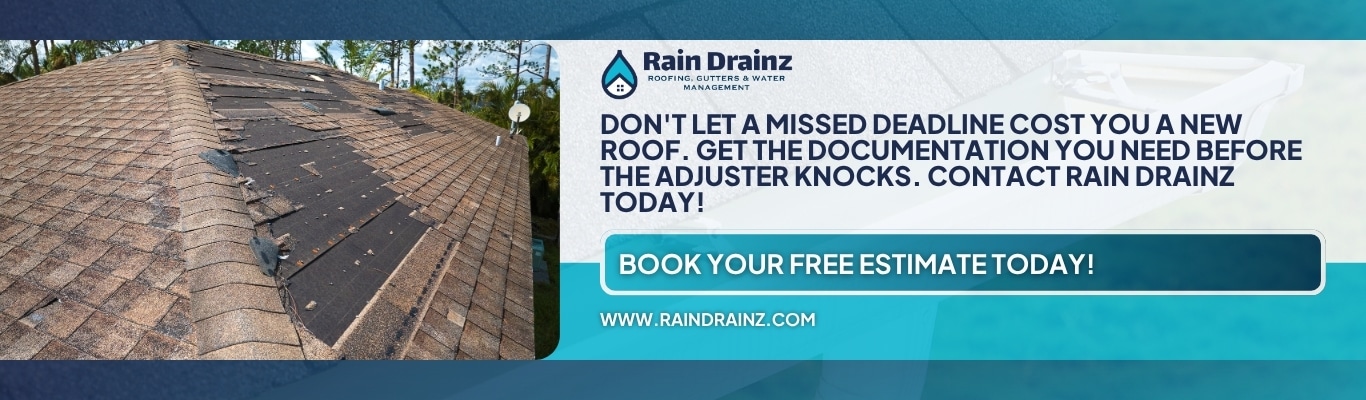
Don’t Let a Missed Deadline Cost You a New Roof
Storm-damaged roofs don’t wait, and neither do insurance filing deadlines.
Preventing Wilmington claim denials requires fast timing, solid documentation, and a certified roofer.
Rain Drainz specializes in storm damage inspections, insurance documentation support, and roof replacement in Wilmington for Delaware homeowners.
Deciding on whether it’s worth claiming roof damage on insurance; or you’re already mid-process?
Their certified GAF team explains your roof coverage before the adjuster arrives.
Protect your claim before it’s too late; contact Rain Drainz.
FAQs About Does Homeowners Insurance Cover Roof Damage
Will insurance cover storm damage to my roof?
Standard homeowners policies cover sudden storm damage when backed by time-stamped photos and a roofer’s inspection.
However, payout depends on your policy type.
Actual Cash Value pays the depreciated value, but Replacement Cost Value covers the full replacement minus your deductible.
Is it worth claiming roof damage on insurance?
Filing is worth it if storm damage exceeds your deductible by $1,500.
For instance, a 2% Delaware deductible on a $300,000 home requires $6,000 out-of-pocket first.
Pay for minor repairs ($350 to $850) out of pocket to protect your premiums, but file for full $10,000 to $15,000 replacements.
How long do I have to file a roof storm-damage claim in Delaware?
Delaware policies require storm damage reporting within a strict 12-month window or face automatic denial.
This initial filing deadline is separate from your legal rights.
While state law allows three years to sue an insurer, it does not override your policy’s mandatory 12-month claim window.